What is the scope and industry significance of the Digital Oilfield Solutions Market?
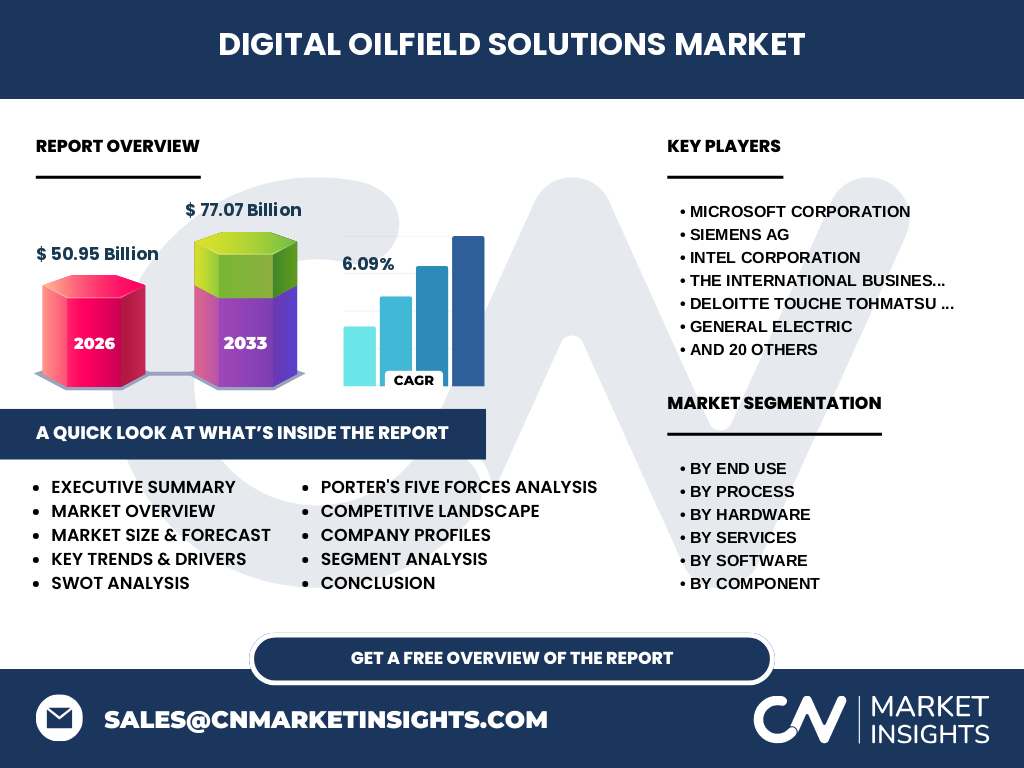
Our analysis indicates that the Digital Oilfield Solutions Market commands a valuation of 50.95 Billion in 2026. This ecosystem integrates advanced edge sensors, SCADA architectures, and cloud analytics to optimize hydrocarbon extraction across upstream, midstream, and downstream operations, mitigating harsh logistical hurdles in remote drilling basins.
What are the core market drivers, restraints, challenges, and opportunities shaping the Digital Oilfield Solutions Market?
The market is propelled by a CAGR of 6.09%, driven by the urgent need for remote asset monitoring under strict OSHA and EPA environmental mandates. However, legacy infrastructure integration bottlenecks and complex cybersecurity threats across SCADA frameworks act as major restraints for operators.
Structural Growth Trends in the Digital Oilfield Solutions Market
Industry trends show a heavy migration toward Internet Of Things (IoT) platforms and Artificial Intelligence algorithms. Operators leverage edge computing to process high-frequency seismic telemetry in real time, reducing non-productive rig time across complex offshore and shale plays.
How did the COVID-19 pandemic impact the Digital Oilfield Solutions Market and its recovery trajectory?
The pandemic compressed upstream capital expenditure, forcing a rapid pivot toward touchless remote operations. This crisis ultimately accelerated cloud adoption and automated production optimization, laying the groundwork for robust post-pandemic recovery reaching a forecasted 77.07 Billion by 2033.
Competitive Benchmarking within the Digital Oilfield Solutions Market
The competitive landscape features integrated oilfield service giants like Schlumberger Limited and Baker Hughes Inc., alongside tech titans such as Microsoft Corporation and IBM. These players compete by bundling proprietary reservoir optimization software with edge hardware infrastructure.
Executive Summary of the Digital Oilfield Solutions Market Analysis
Reaching 77.07 Billion by 2033 from 50.95 Billion in 2026 at a 6.09% CAGR, the market rewards vendors combining domain expertise with advanced data analytics. Companies prioritizing interoperable IoT platforms capture significant enterprise wallet share.
Market Forecast and Long-Term Projections for the Digital Oilfield Solutions Market
Driven by sustained global energy demand and brownfield decline mitigation, the market expands steadily from 50.95 Billion in 2026 to 77.07 Billion by 2033. This growth trajectory reflects a steady 6.09% CAGR anchored by software and digital service expansion.
Segmentation Breakdown of the Digital Oilfield Solutions Market
The market bifurcates by component into Hardware, Software, and Services. Technology segments encompass Internet Of Things (IoT), Artificial Intelligence, and Big Data Analytics, while end-use categories span upstream, midstream, and downstream operations.
Geographic Distribution and Performance Across Regional Markets
North America dominates deployment due to mature shale plays and stringent environmental compliance needs. Meanwhile, the Middle East and Africa exhibit rapid adoption rates driven by national oil companies modernizing massive onshore and offshore extraction sites.
In-Depth Regional Review of Digital Oilfield Deployments
North American basins lead in SCADA and asset management software utilization, whereas Asia-Pacific displays high growth in greenfield downstream refinery automation projects. Localized regulatory pressures in Europe further accelerate green-energy digital tracking systems.
Strategic Positioning of Leading Companies in the Digital Oilfield Solutions Market
Industry leaders like Schlumberger Limited, Halliburton Company, and Emerson Electric Co. leverage deep domain expertise to deliver end-to-end automation. Meanwhile, software-focused innovators like Microsoft Corporation provide the hyper-scale cloud infrastructure necessary for enterprise-wide data ingestion.
Porter's Five Forces Assessment of Competitive Intensity
Supplier power remains moderate due to specialized sensor hardware dependencies, while buyer power is high as supermajors demand customized, interoperable IoT platforms. Threat of substitution is low given the mission-critical nature of real-time drilling optimization software.
SWOT Analysis of the Digital Oilfield Solutions Market
Key strengths include high operational efficiency gains and predictive maintenance capabilities. Weaknesses involve high initial CapEx for legacy retrofits. Opportunities lie in automated decarbonization tracking, while threats center on sophisticated cyberattacks targeting critical energy infrastructure.
Value Chain Analysis from Raw Materials to End-Users
The value chain flows from silicon raw material providers and sensor hardware manufacturers to software developers offering AI analytics, ultimately delivering actionable intelligence to upstream asset managers and downstream refiners seeking reduced downtime.
Investment Insights and Strategic Recommendations for Market Stakeholders
Investors should target niche firms specializing in cybersecurity and predictive maintenance software. Our research indicates that interoperable cloud-native platforms yield the highest margin expansion opportunities as operators shift away from fragmented legacy architectures.
Conclusion and Definitive Takeaways from the Research
The Digital Oilfield Solutions Market presents compelling long-term fundamentals, scaling from 50.95 Billion to 77.07 Billion. Success hinges on robust cybersecurity integration and seamless hardware-software interoperability across global energy assets.
Research Methodology and Baseline Triangulation
Baseline estimates are triangulated by cross-referencing primary stakeholder interviews with C-level executives, trade registry import-export data, and secondary macroeconomic indicators sourced from agencies like the EIA and OPEC.
Scope of the Report and Coverage Parameters
This report covers global deployment revenues from 2026 through 2033, analyzing hardware, software, and services across upstream, midstream, and downstream verticals. Limitations exclude localized underground exploratory expenditures not captured by public corporate reporting.
Recent Industry Developments, Partnerships, and Strategic Moves
Recent strategic activity features major cloud-provider partnerships with oilfield services firms to deploy generative AI for automated well log interpretation. These alliances underscore the industry's rapid transition toward cognitive digital twins and autonomous operations.